
Accounting & Auditing
AI for Professionals
Reading time: Approximately 12–15 minutes
Focus keyword: AI Skills Employers Are Looking for in Young Professionals
Editorial note: Your request contains two different word-count requirements: approximately 1,000 words and a minimum of 3,000 words. The article below follows the longer-form requirement. The provided XML does not contain related keywords, long-tail keywords, or cluster article titles, so those sections have been developed using relevant accounting and auditing concepts.
Introduction: Why AI Skills Employers Are Looking for in Young Professionals Matter to Auditors
The accounting profession is changing rapidly, and AI Skills Employers Are Looking for in Young Professionals increasingly include data analysis, technology literacy, critical thinking, and the ability to interpret complex information. These skills are particularly valuable in auditing, where professionals must examine financial records, identify unusual transactions, and evaluate the reliability of internal controls. As businesses process larger volumes of financial data, artificial intelligence (AI) offers auditors new ways to detect suspicious transactions, prioritize risks, and improve audit efficiency. For professionals developing their careers, understanding how AI supports financial analysis and fraud risk assessment is an important step toward remaining relevant in a technology-driven workplace. This article explains practical AI applications, limitations, and implementation considerations for auditors.
What Are Suspicious Transactions in Auditing?
A suspicious transaction is a financial activity that presents unusual characteristics, potential control weaknesses, or circumstances requiring further investigation. It doesn’t automatically indicate fraud. Instead, it signals that an auditor should obtain additional evidence before reaching a conclusion.
Suspicious transactions may appear in several areas of an organization’s financial operations, including:
- Procurement: Invoices with unusual amounts, repeated payments, or transactions involving related suppliers.
- Payroll: Duplicate employee records, unexpected salary changes, or payments to inactive employees.
- Revenue: Unusual sales near the end of a reporting period, unexplained credit notes, or inconsistent customer activity.
- Cash and banking: Unusual transfers, unexplained withdrawals, or payments outside normal approval procedures.
- Expenses: Duplicate receipts, unsupported claims, and expenses that don’t match organizational policies.
Traditional auditing procedures often involve sampling transactions, reviewing supporting documents, and testing internal controls. Although these approaches remain important, AI can help analyze extensive datasets and highlight patterns that deserve closer attention.
The auditor’s responsibility is to assess the evidence, consider the relevant circumstances, and determine whether further procedures are necessary. A transaction identified by AI should therefore be treated as an investigative lead rather than proof of wrongdoing.
How AI Skills Employers Are Looking for in Young Professionals Support Suspicious Transaction Detection
AI Skills Employers Are Looking for in Young Professionals extend beyond the ability to operate an AI chatbot. In auditing, useful capabilities include understanding financial data, identifying patterns, evaluating analytical outputs, and applying professional judgment.
AI-powered audit tools may use machine learning, statistical analysis, rule-based systems, and natural language processing to examine financial records.
1. Machine Learning for Anomaly Detection
Machine learning models can analyze historical transaction data to identify activities that differ from established patterns.
For example, a model may learn that most supplier payments within a company fall between GH¢500 and GH¢15,000. If a payment of GH¢85,000 appears in an unusual account, the system may flag it for review.
However, an unusual amount isn’t necessarily fraudulent. A legitimate equipment purchase, annual insurance payment, or emergency procurement could explain the difference.
The auditor must consider:
- The transaction’s business purpose.
- The supplier’s history.
- Approval and authorization records.
- Supporting invoices and delivery documentation.
- Whether the transaction is consistent with the organization’s policies.
Machine learning can help identify candidates for testing, but the final assessment must be based on appropriate audit evidence.
2. Rule-Based Detection
Not every AI-assisted detection system requires complex machine learning. Rule-based analytics can also be useful.
Examples include flagging:
- Two invoices with the same invoice number.
- Payments processed just below an approval threshold.
- Transactions posted on weekends or public holidays.
- Repeated payments to the same supplier within a short period.
- Journal entries posted by users without appropriate authorization.
Rules can be designed around an organization’s accounting policies, approval limits, and risk profile. Their effectiveness depends on accurate configuration and regular review.
3. Natural Language Processing
Natural language processing (NLP) can help examine textual information, including invoice descriptions, payment narratives, and expense explanations.
For instance, an audit team may analyze thousands of transaction descriptions to identify common terms associated with unusual purchases or unclear business purposes.
NLP can assist with organizing and prioritizing records, but text-based indicators should be interpreted carefully. Different employees may describe legitimate transactions in inconsistent ways, and suspicious language alone doesn’t establish misconduct.
Practical Ways Auditors Can Use AI to Identify Suspicious Transactions
The value of AI becomes clearer when its applications are connected to everyday audit procedures. Auditors don’t need to automate every part of an engagement. Instead, they can introduce targeted analytical procedures that support existing methodologies.
1. Analyze Large Volumes of Transaction Data
One of the major advantages of AI-assisted analytics is its ability to process large datasets.
Consider a company with 250,000 purchase transactions in one financial year. Reviewing every transaction manually may require substantial time and resources. An analytical system can examine the population and identify records with characteristics such as:
- Unusual transaction values.
- Duplicate supplier invoices.
- Repeated payments on the same date.
- Unusual timing or posting patterns.
- Unexpected changes in supplier activity.
The auditor can then review the flagged transactions and compare the results with the organization’s procurement policies and supporting records.
This approach can improve the prioritization of audit work, although data completeness and accuracy must be assessed before the results are relied upon.
2. Detect Duplicate Invoices and Payments
Duplicate payments are a practical area where data analytics can support internal controls.
A company may accidentally pay the same invoice twice because of duplicate data entry, invoice resubmission, or weaknesses in the accounts payable process. In other cases, deliberate duplication may be suspected.
AI-assisted systems can compare combinations of:
- Supplier identification.
- Invoice numbers.
- Invoice dates.
- Invoice amounts.
- Purchase order references.
- Bank account details.
Exact duplicates are relatively straightforward to identify. More advanced systems may also detect potential duplicates where invoice numbers differ slightly, descriptions have been modified, or amounts have been split across several records.
For example, the following payments might warrant review:
|
Supplier
|
Invoice
|
Amount
|
Observation
|
| — | — | — | — |
|
Supplier A
|
INV-1045
|
GH¢4,800
|
Original invoice
|
|
Supplier A
|
INV-1045
|
GH¢4,800
|
Same invoice reference
|
|
Supplier A
|
INV-1046
|
GH¢4,800
|
Similar amount and timing
|
The third payment isn’t necessarily fraudulent, but the pattern may require reconciliation against delivery records and the supplier’s statement.
The auditor should verify the underlying evidence rather than assume that similar amounts represent duplicate payments.
3. Identify Unusual Journal Entries
Journal entry testing is an important part of many financial statement audits.
AI-assisted analytics can help auditors examine entries based on characteristics such as:
- Entries posted near the financial year-end.
- Manual journals with unusual descriptions.
- Entries posted by users outside their normal responsibilities.
- Unusual account combinations.
- Large or infrequently used adjustments.
- Entries posted and reversed shortly afterward.
For example, a manual journal could increase revenue and receivables shortly before year-end. The auditor might investigate whether the entry is supported by a genuine sale, whether the recognition criteria have been met, and whether the transaction was properly authorized.
AI can help prioritize entries, but the auditor must apply the relevant accounting framework and professional standards when evaluating the transaction.
For additional professional development, accountants can explore how financial reporting skills and analytical tools work together through practical learning resources from IFAC .
4. Detect Unusual Supplier Transactions
Supplier analytics can help identify patterns that may indicate weaknesses in procurement controls.
An organization may have hundreds of suppliers, with different payment terms, purchasing categories, and approval requirements. AI-assisted tools can analyze supplier activity to identify unusual patterns.
Potential indicators include:
- A new supplier receiving unusually high payments soon after registration.
- Multiple suppliers sharing the same bank account.
- Payments made outside agreed contractual terms.
- Unusual concentration of purchases with a single supplier.
- Transactions that bypass normal purchase order procedures.
These indicators require context. For instance, several suppliers might legitimately use a common payment account because they belong to the same corporate group.
Auditors should therefore examine supplier master data, contracts, ownership information, and procurement approvals before drawing conclusions.
AI Skills Employers Are Looking for in Young Professionals: Data Analytics for Audit Planning
Risk-Based Audit Prioritization
Not every unusual transaction carries the same level of risk. An isolated small-value transaction may require a different response from a recurring pattern involving a high-value supplier.
Auditors can combine transaction analytics with other information, such as:
- Materiality.
- Fraud risk assessments.
- Control deficiencies.
- Management override risks.
- Prior audit findings.
- Changes in business processes.
A risk-based approach allows audit teams to allocate their resources more deliberately.
For example, an internal audit department may discover that a particular branch has experienced repeated payment approval exceptions. AI-assisted analytics could help identify the transactions involved, while auditors investigate the underlying control environment.
The result should be a documented audit response, not an automated accusation.
Example: A Microfinance Institution
Consider a fictional microfinance institution that processes thousands of loan disbursements and repayments.
An AI-assisted analytical system identifies the following pattern:
- Several loan applications are linked to the same contact details.
- A number of disbursements were approved outside normal working hours.
- Certain loan officers have unusually high approval activity.
- Some repayments are posted shortly after disbursement.
These observations may warrant investigation, but they don’t independently establish fraud. Legitimate explanations could include shared contact information, authorized after-hours processing, or repayment arrangements that are consistent with the institution’s lending policy.
The audit team could:
- Review the relevant loan files.
- Compare borrower identification records.
- Examine approval logs and user access permissions.
- Reconcile disbursement and repayment records.
- Interview responsible officers.
- Assess whether controls were followed.
The analytical system supports the process by helping the auditors identify where additional evidence may be needed.
How to Implement AI in an Audit Process
Introducing AI into auditing requires more than purchasing software. The organization must establish a process for data preparation, analytical review, documentation, and oversight.
Step 1: Define the Audit Objective
Before using an AI tool, auditors should clarify what they want to identify.
For example:
- Detect duplicate payments.
- Review unusual journal entries.
- Analyze supplier transactions.
- Identify exceptions to approval limits.
- Assess patterns in expense claims.
A clearly defined objective helps determine the relevant data, analytical approach, and expected output.
Step 2: Obtain Reliable Financial Data
The quality of AI-generated results depends heavily on the quality of the underlying data.
Auditors should assess:
- Completeness of transaction records.
- Accuracy of account codes.
- Consistency of supplier identifiers.
- Reliability of transaction dates.
- Availability of approval information.
- Reconciliation between source systems and the general ledger.
Missing or inaccurate information can create false positives or conceal important transactions.
The NIST AI Risk Management Framework provides a useful reference for organizations considering AI risk management and trustworthy AI practices.
Step 3: Select an Appropriate Analytical Method
Different objectives require different tools.
|
Audit objective
|
Potential method
|
| — | — |
|
Identify exact duplicate invoices
|
Rule-based matching
|
|
Detect unusual transaction values
|
Statistical analysis
|
|
Review unusual journal entries
|
Rules and anomaly detection
|
|
Analyze invoice descriptions
|
Natural language processing
|
|
Identify complex transaction patterns
|
Machine learning
|
A simple analytical method may be sufficient for a well-defined control test. Advanced AI isn’t automatically necessary for every audit problem.
Step 4: Validate the Results
AI-generated results should be tested before being incorporated into audit conclusions.
Validation may involve:
- Reviewing a sample of flagged transactions.
- Comparing results with known exceptions.
- Checking whether legitimate transactions are frequently flagged.
- Assessing whether important suspicious patterns are missed.
- Confirming that the model or rules work consistently.
Auditors should document the analytical method, data used, assumptions, limitations, and validation procedures.
Step 5: Investigate and Document Findings
Once suspicious transactions are identified, auditors should conduct appropriate follow-up procedures.
The investigation may involve reviewing original documentation, obtaining confirmations, interviewing employees, and testing relevant controls.
Findings should be supported by evidence and communicated through the appropriate audit reporting process.
AI-generated explanations should not replace the auditor’s own documentation and professional assessment.
Benefits of Using AI for Suspicious Transaction Detection
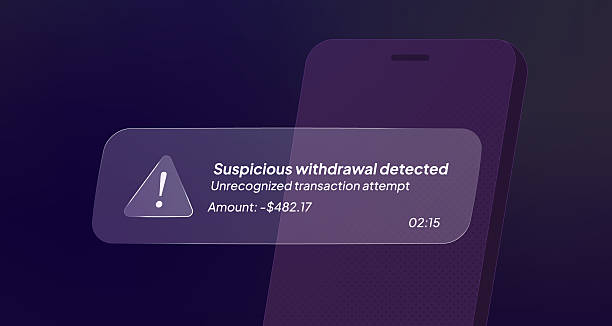
Improved Efficiency
AI can help automate repetitive data analysis, allowing auditors to spend more time evaluating exceptions and investigating control weaknesses.
Broader Transaction Coverage
Analytical tools can review large populations of transactions instead of relying exclusively on small samples. This may help identify patterns that sampling doesn’t capture.
However, reviewing a larger population doesn’t eliminate the need for professional judgment, audit evidence, or appropriate testing.
Faster Risk Identification
AI can help audit teams prioritize unusual transactions earlier in an engagement, potentially improving the allocation of audit resources.
Consistent Analytical Procedures
Well-designed rules and documented procedures can help apply the same analytical criteria across relevant transaction populations.
The results must still be monitored to ensure that the criteria remain appropriate.
Support for Continuous Auditing
Organizations with suitable systems may use automated analytics to monitor transactions periodically or continuously.
This can support timely identification of exceptions, particularly in environments with high transaction volumes.
The extent of automation should depend on the organization’s risk profile, data infrastructure, governance, and audit objectives.
Limitations and Risks of AI in Auditing
Although AI offers practical benefits, it introduces risks that auditors and organizations must manage carefully.
False Positives
A false positive occurs when a system flags a transaction as unusual even though it is legitimate.
For example, an unusually large payment may relate to an approved capital expenditure project. Excessive false positives can increase review workloads and reduce confidence in the analytical process.
False Negatives
A false negative occurs when a suspicious transaction isn’t identified by the system.
This is particularly important because fraud can be deliberately concealed, and historical patterns may not reveal newly emerging methods.
AI should therefore not be treated as a guarantee that all fraudulent activity will be detected.
Data Privacy and Confidentiality
Financial data may contain sensitive information, including employee details, customer records, bank account information, and confidential business transactions.
Auditors should use approved systems, follow organizational policies, and ensure that data access is appropriately controlled.
Sensitive accounting records should not be uploaded to public AI tools without authorization and suitable safeguards.
Algorithmic Bias
An AI system may produce uneven results when its training data or design assumptions are unsuitable for the audit population.
For example, a model trained on historical transactions may incorrectly treat legitimate transactions from a new business unit as suspicious.
Auditors should consider whether the system’s assumptions are appropriate and whether the results are consistent across relevant groups.
Explainability
Auditors need to understand why a transaction was flagged.
A system that produces a risk score without a meaningful explanation may be difficult to evaluate and document. The extent of explainability required depends on the analytical method and the audit purpose.
Overreliance on Technology
AI should support professional judgment, not replace it.
The Institute of Internal Auditors emphasizes governance, data quality, ethics, and accountability in its Artificial Intelligence Auditing Framework . This guidance is relevant when organizations develop controls around AI use and audit-related activities.
How Young Auditors Can Develop Relevant AI Skills
The growing use of technology in auditing creates opportunities for professionals to develop a combination of accounting expertise and digital capabilities.
Learn Excel and Data Analytics
Excel remains a useful tool for organizing financial data, reconciling records, performing calculations, and reviewing audit exceptions.
Young auditors can strengthen their capabilities by learning:
- Pivot tables.
- XLOOKUP and other lookup functions.
- Conditional formatting.
- Data cleaning.
- Power Query.
- Basic dashboard development.
These skills create a practical foundation for more advanced analytics.
Understand AI Fundamentals
Auditors don’t necessarily need to become machine learning engineers. However, they should understand basic concepts such as:
- Machine learning.
- Anomaly detection.
- Predictive analytics.
- Data quality.
- Model limitations.
- AI governance.
Understanding these concepts helps auditors ask relevant questions and evaluate the reliability of AI-assisted outputs.
Develop Critical Thinking
Technology skills should be combined with professional skepticism and analytical reasoning.
An auditor should be able to ask:
Why was this transaction flagged, and what evidence would confirm or contradict the concern?
This question encourages evidence-based investigation rather than automatic acceptance of AI-generated results.
Practice Responsible AI Use
Young professionals should understand confidentiality, data protection, appropriate tool selection, and the risks of inaccurate AI-generated information.
For accounting students and professionals in Ghana, institutions such as ICAG can serve as an important reference point for continuing professional development and accounting knowledge. AI skills should complement, rather than replace, the technical foundations of auditing and financial reporting.
Practical AI Prompts Auditors Can Use
Generative AI tools can assist with certain low-risk analytical and documentation tasks when approved by the organization and used with appropriate safeguards.
The following prompts are illustrative. They should be applied to anonymized or authorized data, and outputs must be independently verified.
Prompt 1: Identify Potential Duplicate Transactions
“Review this anonymized transaction dataset. Identify records with matching supplier identifiers, invoice numbers, dates, and amounts. Present potential duplicate groups and explain which fields contributed to each match. Do not conclude that any transaction is fraudulent.”
Prompt 2: Review Journal Entry Exceptions
“Analyze the provided anonymized journal entry data against the stated review criteria. Highlight entries posted outside normal working hours, entries above the defined threshold, and unusual account combinations. Clearly distinguish observations from conclusions.”
Prompt 3: Develop an Audit Investigation Checklist
“Create a checklist for investigating unusual supplier payments. Include documentation review, authorization checks, supplier verification, bank reconciliation, and appropriate evidence requirements.”
These prompts can support planning and organization, but they aren’t substitutes for specialized audit analytics, reliable data processing, or professional review.
The Future of AI-Assisted Auditing
AI-assisted auditing is likely to continue developing as organizations improve their data systems and adopt new technologies.
Future applications may include more integrated transaction monitoring, improved anomaly detection, automated document comparison, and enhanced analytical support for internal audit teams.
However, successful adoption will depend on more than technological capabilities. Organizations will need suitable governance, data quality controls, cybersecurity measures, clear responsibilities, and appropriate human oversight.
The IIA’s AI resources provide a useful starting point for internal auditors who want to understand AI-related risks and develop assurance approaches. Its guidance can be explored through the IIA Artificial Intelligence Knowledge Center .
Auditors who develop both accounting knowledge and technological competence will be better positioned to participate in these changes. The exact skills required will vary according to the organization’s systems, audit methodology, industry, and regulatory environment.
Conclusion: Building the Future of Auditing with AI
AI provides auditors with practical ways to analyze financial transactions, identify unusual patterns, and prioritize investigative work. From detecting duplicate invoices to reviewing journal entries and analyzing supplier activity, AI-assisted analytics can strengthen the way audit teams approach large volumes of financial data.
However, suspicious transaction detection must remain an evidence-based process. An unusual transaction isn’t automatically fraudulent, and AI-generated results should be validated through appropriate audit procedures.
For young professionals, developing AI Skills Employers Are Looking for in Young Professionals means combining accounting expertise, data analytics, critical thinking, and responsible technology use. These capabilities can help auditors adapt to evolving workplace expectations while maintaining the professional judgment and accountability that underpin effective auditing.
Through continuous learning and practical application, accounting professionals can use AI as a tool to improve audit efficiency, support risk assessment, and contribute meaningful insights to their organizations.
Recommended External Resources
|
Resource
|
Purpose
|
| — | — |
|
The Institute of Internal Auditors – AI Auditing Framework
|
AI governance, risks, and internal audit guidance
|
|
IIA Artificial Intelligence Knowledge Center
|
AI resources and learning materials for internal auditors
|
|
NIST AI Risk Management Framework
|
AI risk management and trustworthy AI concepts
|
|
NIST Adversarial Machine Learning Report
|
AI security risks and mitigation concepts
|
Knowsia connection: Knowsia is an e-learning platform that can support accounting and finance professionals in developing practical digital skills, including AI-assisted financial analysis, automation, and professional development.